


Own the program, not just the policy
Helio Risk forms and manages captive insurance programs from the first business plan through ongoing claims, so the business that takes the risk also owns the upside.
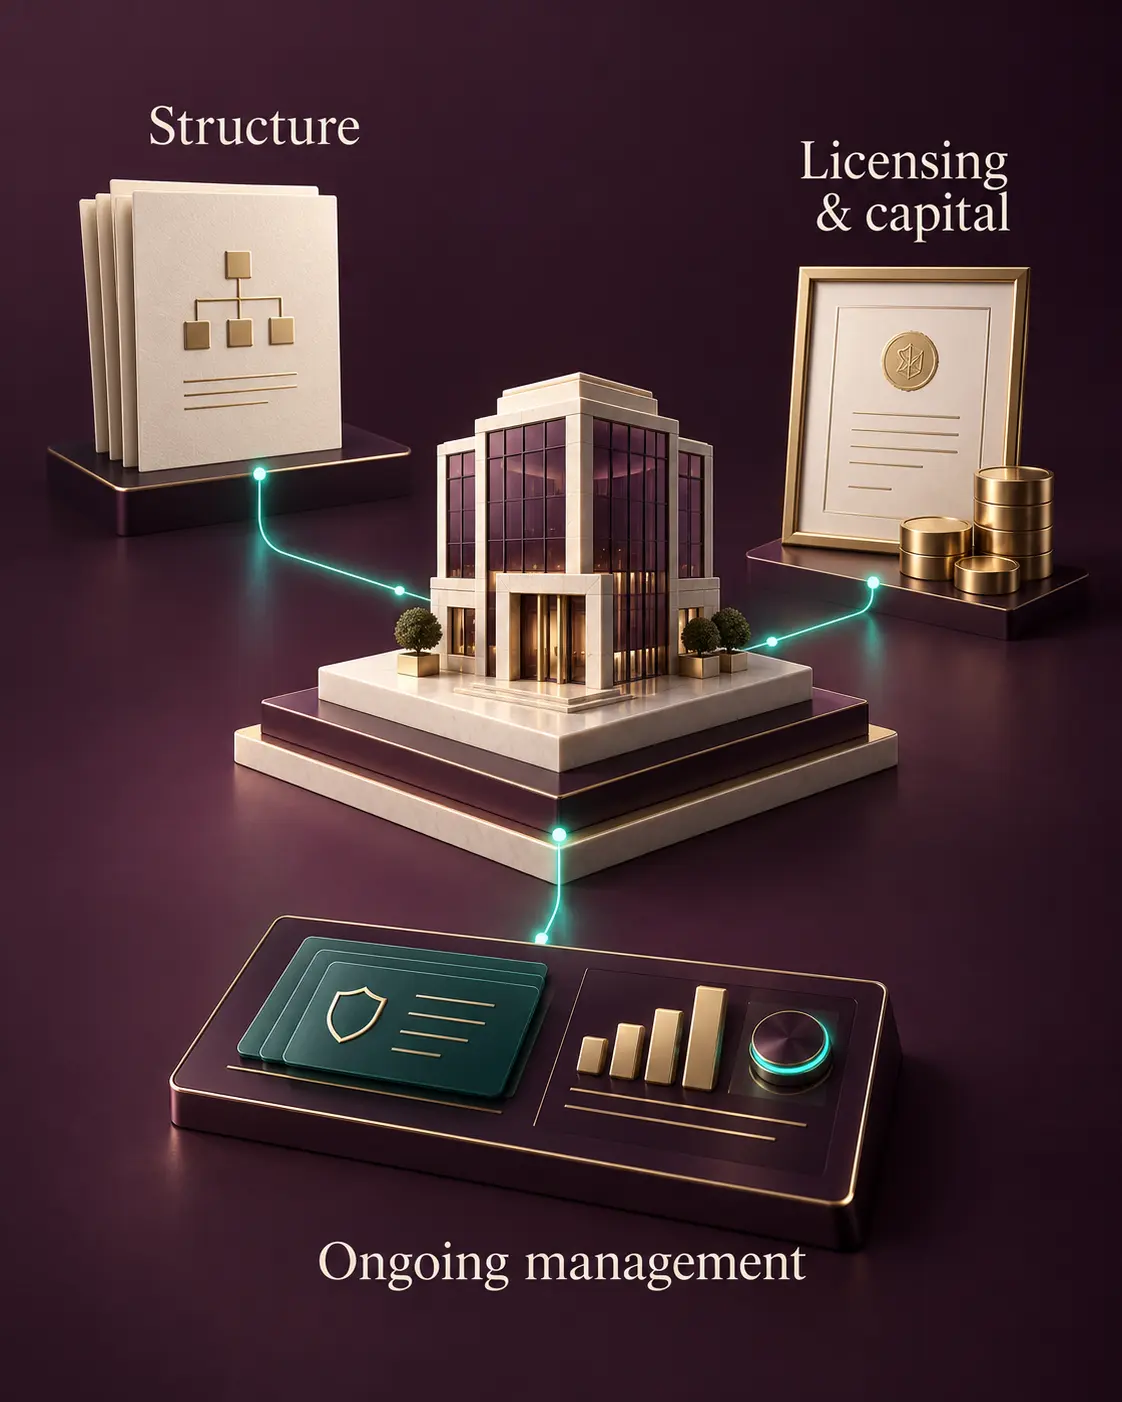
What is included in formation and management?
A captive is its own licensed insurance company, owned by your business. Helio Risk builds it, licenses it and runs it, so your team stays focused on running the business.
Structure & documents
Corporate structure, financials and the legal documents a regulator expects to see.
Licensing & capital
EIN, capital contribution and license issuance, with regulatory review.
Ongoing management
Policy issuance, premium collection, loss payment and corporate governance after launch.
The formation process, in three phases
The same three phases every Helio Risk captive goes through, start to finish. Ongoing management continues after approval for as long as the program runs.
1. Business plan
Corporate structure, financials and internal approvals go on paper before anything is filed.
2. Application
A pre-application meeting, EIN, capital contribution and license issuance, with regulatory review timing that depends on the domicile and the application itself.
3. Approval
Policy issuance, premium collection, loss payment and corporate policy adoption bring the captive to life, then Helio Risk manages it going forward.
Who this is for
A good fit
- Businesses with real, measurable, repeatable risk
- Owners ready to fund risk instead of only transferring it
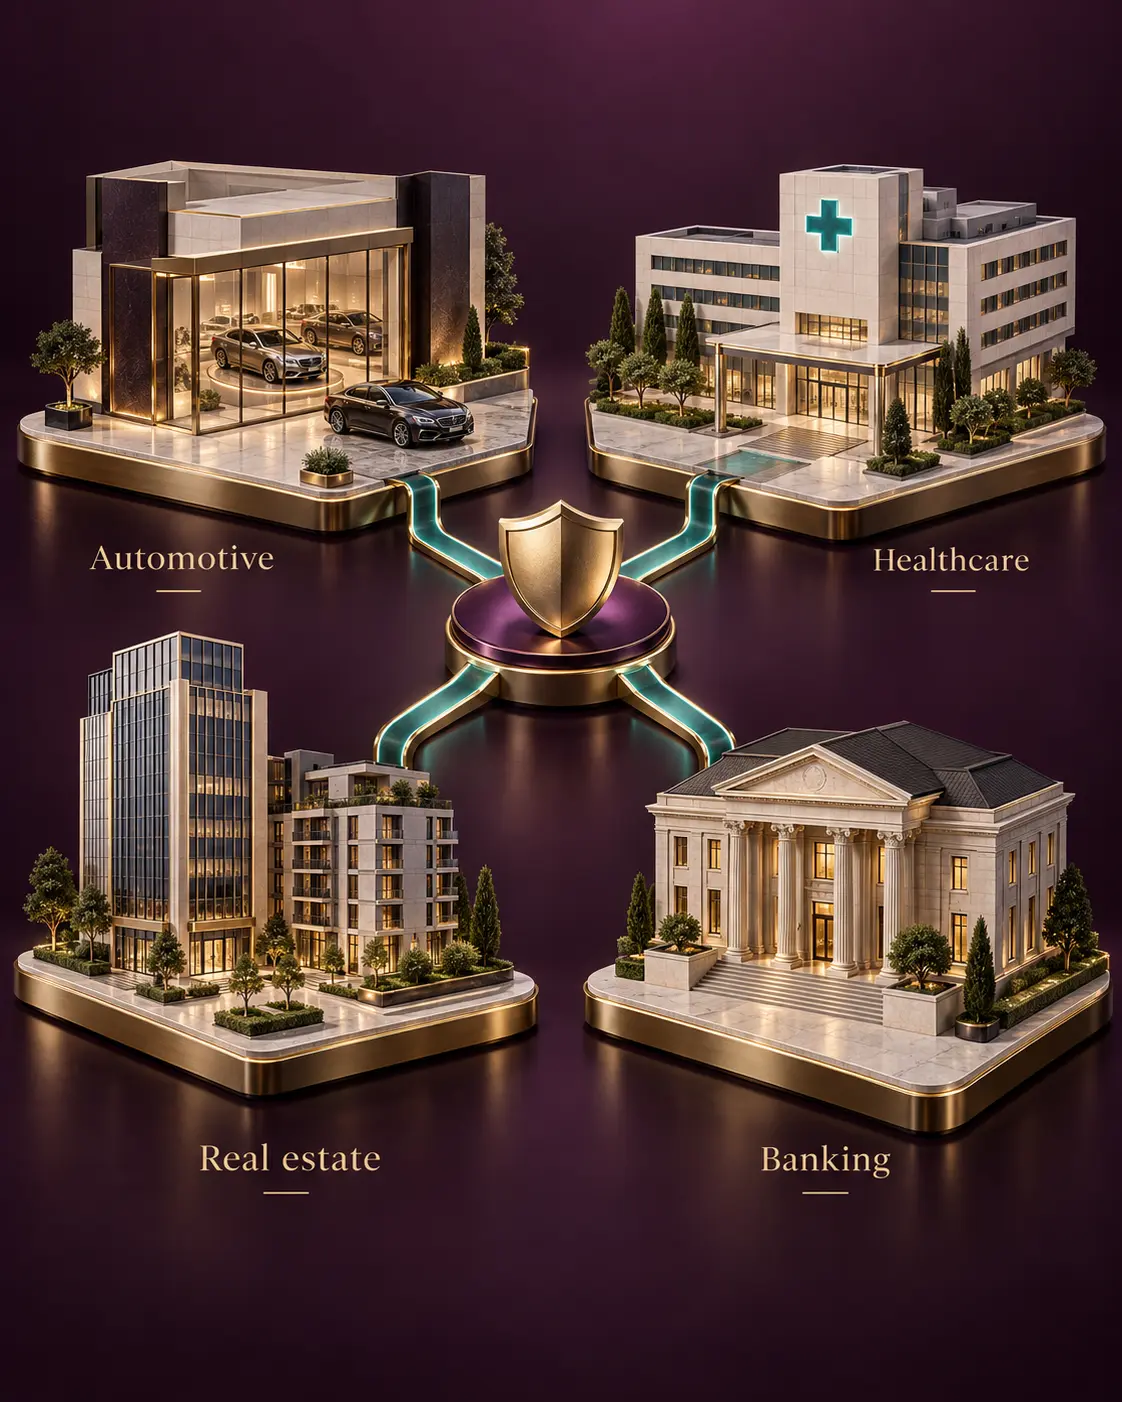
- Companies in automotive, healthcare, real estate, banking and similar industries
Not the right fit
- Businesses looking only to lower a premium this year
- Anyone unwilling to hold capital in the program long term
Captive formation questions
Formation runs in three phases. The business plan phase covers corporate structure, financials and internal approvals. The application phase includes a pre-application meeting, EIN, capital contribution and license issuance, with regulatory review of about 30 days. The approval phase covers policy issuance, premium collection and loss payment.
Business plan, application and approval. The business plan phase covers corporate structure, financials and internal approvals. The application phase includes a pre-application meeting, EIN, capital contribution and license issuance. The approval phase covers policy issuance, premium collection, loss payment and corporate policy adoption.
Once the application phase begins, regulatory review generally runs about 30 days, covering the pre-application meeting, EIN, capital contribution and license issuance.
Corporate structure, financials and internal approvals are put on paper before anything is filed with a regulator, so the captive is built on a plan the business has already agreed to.
Policy issuance, premium collection, loss payment and corporate policy adoption bring the captive to life. From there, Helio Risk manages the program on an ongoing basis rather than handing it off.
Businesses with real, measurable, repeatable risk, and owners ready to fund that risk instead of only transferring it. Companies in industries like automotive, healthcare, real estate and banking are common fits.
Businesses looking only to lower this year's premium, or anyone unwilling to hold capital in the program long term, are not a good match for a captive.

See if a captive fits
An introductory conversation helps identify whether a captive fits your risk profile and what it would take to confirm it.